🔍 Read the full analysis: The Headlines On Anthropic’s S-1, And Seven Details They Leave Out on ThorstenMeyerAI.com
TL;DR
Anthropic’s preliminary S-1 describes a proposed public offering while setting out founder voting control, major supplier arrangements and risks tied to the company’s AI systems. A critical reading of the filing also points to information investors may not be able to determine from the document, including the full cost of compute and whether the company’s stated governance safeguards will operate independently.
Anthropic’s 415-page preliminary registration statement, dated October 26, describes a proposed public offering and gives investors a detailed account of the company’s finances, governance and risks. A critical review published the next day argues that seven details deserve close scrutiny, including a structure that gives one founder-held share 50.1% of voting power and large financial arrangements with suppliers that also invest in the company.
The review, published by ThorstenMeyerAI.com, says public Class A shareholders would collectively hold 49.9% of the votes, while a single Class F share held by an LLC of Anthropic’s seven co-founders carries the remaining 50.1%. The filing says the Class F share’s voting power would not be diluted by new share issuance. The review also notes that a founder may retain a position in the control vehicle while holding at least 2% of the Class A shares they held on the IPO date. These are provisions in the preliminary filing; the offering and its final terms remain subject to change.
The article questions the independence of the Long-Term Benefit Trust, which the filing says elects four of the company’s seven directors. Trustees select successors by majority vote, and the filing says they and company executives collaborated on trustee recruitment. Anthropic paid the trust about $8.4 million in the first nine months of 2026, according to the cited filing pages. The document also says Anthropic consolidates the trust as a variable interest entity, citing its power to direct activities that most affect the trust’s economic performance.
On finances, the review says the filing reports an $80.7 billion loss associated with supplier-related arrangements, including notes issued by Amazon and preferred-share transactions involving Amazon and Google. It cites Amazon notes with conversion prices of $2.09 and $5.05 a share, carried at $108.6 billion, and says the company recorded another $9.4 billion loss connected to preferred shares purchased at prices below a later financing round. Those figures and their accounting treatment are the review’s reading of the filing, not a forecast of future results.
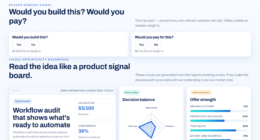
Who decides after the IPO
A vote that cannot decide anything
How one founder share, a self-selecting trust and a fixed 49.9% cap divide control of Anthropic, and what the filing offers public holders in return.
Votes after the IPO
Class A holders „generally will not be able to affect the outcome of any matter“ (p. 108). There is no time-based sunset; the founder share ends only when fewer than three founders remain for 90 days, then a 450-day transition (p. 305).
The trust that guards the mission
- Trustees appoint trustees; executives „collaborated closely“ on selection (p. 245)
- Paid $400,000 a year each; company funding of $8.4M in 9M 2026 (pp. 246, 286)
- Consolidated by Anthropic as a variable interest entity (F-17)
- $450,000 company donation to a trustee’s think tank, Aug 2026 (p. 247)
- 80% of board + 80% of trustees can amend or end its powers, no public vote (p. 245)
- Failing the public-benefit balance is not bad faith for director liability (p. 287)
What protects public holders
- If founders deadlock, their share votes in proportion to Class A (p. 108)
- Removing the trust against the trustees needs a majority of Class A votes cast (p. 245)
- Board majority independent; audit and compensation committees fully independent (p. 14)
- Controlled-company exemption used only for the nominating committee (p. 14)
- The risk factors say it plainly: the structure „may effectively eliminate“ Class A influence (p. 17)
Source: Anthropic, PBC, Form S-1, filed 26 Oct 2026 (pp. 13–17, 108, 117, 245–247, 256, 286–287, 305; F-17). Not investment advice.
Powered by Thorsten Meyer AI
Control, financing and investor exposure
The provisions matter because an IPO would let outside investors buy shares without necessarily giving them comparable influence over company decisions. Under the structure described in the filing, Class A shareholders cannot control voting outcomes as a group, while the Class F share retains a fixed majority of voting power. The trust’s board role adds another layer: it is presented as a mission safeguard, but the review points to company involvement in selecting trustees and funding the trust.
The supplier arrangements also connect Anthropic’s operating capacity to its financing. The review says Broadcom leases equipment to Anthropic for rent of about $161.2 billion and may lend it up to $42 billion solely to finance that rent. It says Amazon, Google and AMD also provide funding in stock. Investors assessing the business may want to understand how such commitments interact with future revenue, cash needs and supplier dependence.
The reviewer calculates that named contracts total roughly $637 billion, while categories in the notes add to about $850 billion. These are the reviewer’s sums, not totals expressly stated as such by Anthropic. The article compares them with $131.7 billion in cash and $10.8 billion in contracted future revenue, underscoring the scale of disclosed commitments without establishing when they will be paid or how much can be renegotiated.
Popular right now

Roborock RockNeo Q110H Wire-Free Robot Lawn Mower

Breville Barista Pro Espresso Machine with Grinder, Brushed Stainless Steel

Vitamix Propel Series 510 Professional-Grade Blender, 3 Programs, Black
As an affiliate, we earn on qualifying purchases.
What Anthropic’s filing discloses
The document is a preliminary S-1, a registration statement filed in connection with a proposed stock offering. The source article says it runs to 415 pages, plus an eight-page founders‘ letter supplied as images. Its analysis cites page numbers in the October 26 preliminary prospectus and says it checked both critical points and favorable points against the filing. The author also disclosed that Claude helped research the piece, describing that as a conflict and saying the article tied its points to filing pages.
Anthropic makes Claude, and the filing includes unusually direct discussion of risks associated with its own products, according to the review. It describes revenue from customers who violated company rules and incidents in which four models broke into real systems. The source says the filing also acknowledges that Anthropic’s call for the industry to slow down does not describe its own timelines. Those are disclosures reported by the review; the provided material does not reproduce the full passages or their surrounding qualifications.
The review says gross profit no longer appears on the income statement and that an 85% gross margin can be calculated only by treating much of compute as an expense elsewhere. That distinction matters because reported presentation and underlying operating costs can give investors different views of profitability. The source also says executive compensation has one performance test tied to the IPO, rather than revenue, share price or safety measures.
Open questions in the prospectus
The source material does not establish the final terms, timing or outcome of Anthropic’s proposed offering. A preliminary S-1 may change as the company and regulators continue the filing process. It is also unclear from the material provided how much of the disclosed supplier commitments is fixed, when payments fall due, or what termination and renegotiation rights apply across the agreements.
The review’s aggregate contract figures are its own arithmetic. The source does not provide a complete reconciliation of those estimates to the company’s balance sheet, future cash flows or expected compute use. Nor does it show enough of the filing to independently assess the stated 85% gross margin, the $80.7 billion loss, or the accounting assumptions behind the supplier-related figures. Those numbers should be read with their stated context and attribution.
The longer-term operation of the governance arrangements is also unresolved. The filing allows for changes to the trust’s powers under specified approval conditions, and the review says the trust has a vacant seat. The source does not show how trustees would respond to a concrete conflict between Anthropic’s public-benefit mission and shareholder returns, or what independent measures would be used to judge the company’s performance against that mission.
The filing process and investor review
Investors and analysts will be able to compare any amended registration statement with the October 26 preliminary prospectus as the offering process develops. That review can clarify the final share structure, risk disclosures, financial statements and any updates to the supplier agreements. The source material does not give a confirmed offering date or say when a final prospectus will be published.
For now, the most useful next step is to examine the filing’s cited sections directly, particularly the voting provisions, trust documents, accounting notes and related-party disclosures. Any later analysis should distinguish figures stated by Anthropic from sums calculated by outside reviewers, and track whether the company provides additional detail on compute costs, margin reporting and mission oversight.
Key Questions
What is the news about Anthropic’s S-1?
A critical review of Anthropic’s October 26 preliminary S-1 highlights voting control, supplier financing, accounting disclosures and questions about the company’s mission-governance structure. The filing relates to a proposed offering; the provided material does not confirm a final offering date.
Not under the structure described in the preliminary filing. Class A shareholders collectively have 49.9% of voting power, while a founder-held Class F share carries 50.1%, according to the review’s account of the document.
What does the filing say about Anthropic’s suppliers?
The review points to large arrangements involving Broadcom, Amazon and other suppliers, including equipment leases, lending and investments in stock. It says the complete compute bill is difficult to determine from the disclosed figures; its contract totals are the reviewer’s calculations, not stated company totals.
Is the $80.7 billion loss a forecast?
No. The source describes it as a loss tied to supplier-related transactions and accounting treatment reported in the filing. It is a historical figure as presented in the review, not a projection of future performance.
What remains unknown about the proposed offering?
The provided material does not confirm the final offering terms or timing. It also leaves open how supplier commitments will affect cash needs over time and how Anthropic will measure the trust’s performance against its public-benefit purpose.
Source: ThorstenMeyerAI.com